AADR: 3rd Quarter 2026 Portfolio Review

Performance data quoted represents past performance and is no guarantee of future results. Current performance may be lower or higher than the performance data quoted. Investment return and principal value will fluctuate so that an investor’s shares, when redeemed, may be worth more or less than original cost. Returns less than one year are not annualized. For the fund’s most recent standardized and month-end performance, please click www.advisorshares.com/etfs/aadr.

Strategy

The AdvisorShares Dorsey Wright ADR ETF’s (AADR) strategy uses relative strength to allocate towards the strongest performing ADR’s in Developed and Emerging Markets. The strategy starts with a top down approach, first ranking each sector based on its relative strength scores and then setting the weighting of each sector. Holdings are scored daily based on an in-house momentum score which compares each security to the peers in the universe. If a securities rank falls below our sell threshold, it is removed. The strategy is not constrained to holding a set allocation to Emerging or Developed Markets, rather the process identifies areas of strength across the globe regardless of geographical location. This allows the portfolio to over or underweight regions and markets to concentrate on areas of strength, often pushing the portfolio to vary dramatically from international benchmarks.

Performance

For the third quarter, AADR returned −0.79% (NAV) | −0.14% (market), compared with 0.81% for the MSCI EAFE Index (Net) and 0.10% for the BNY Mellon Classic ADR Index. Holdings such as Ultrapar Participações (UGP), VEON (VEON), and Sasol (SSL), each up more than 40% for the quarter, were among the fund’s strongest contributors, but their gains were more than offset by losses in positions including China Yuchai International (CYD) and Nokia (NOK).

Holdings

The portfolio continues to be allocated to securities we believe display favorable relative strength characteristics. At any given time, the portfolio will be comprised of 30-40 US traded ADR’s from our universe of 300-450 ADR’s. Currently, the portfolio consists of 36 securities with weights ranging from ~1.49% to ~5.68% with the top 10 holdings comprising roughly 38% of the portfolio.  The portfolio increased exposure to Belgium, Panama, Switzerland, Germany, Netherlands, and the UK over the quarter while decreasing exposure to South Africa, Japan, France, Singapore, Brazil, and Sweden.

Top 10 Holdings

Ticker Security Description Portfolio Weight %
BBVA BANCO BILBAO VIZCAYA-SP ADR 5.62%
MUFG MITSUBISHI UFJ FINL-SPON ADR 5.28%
BVN CIA DE MINAS BUENAVENTUR-ADR 3.78%
BCS BARCLAYS PLC-SPONS ADR 3.74%
TSM TAIWAN SEMICONDUCTOR-SP ADR 3.68%
SMFG SUMITOMO MITSUI-SPONS ADR 3.45%
UGP ULTRAPAR PARTICPAC-SPON ADR 3.35%
TEVJF TEVA PHARMACEUTICAL IND LTD 3.16%
RYCEY ROLLS-ROYCE HOLDINGS-SP ADR 2.94%
NOK NOKIA CORP-SPON ADR 2.91%

As of 09.30.2026. Holdings are subject to change.

Geography
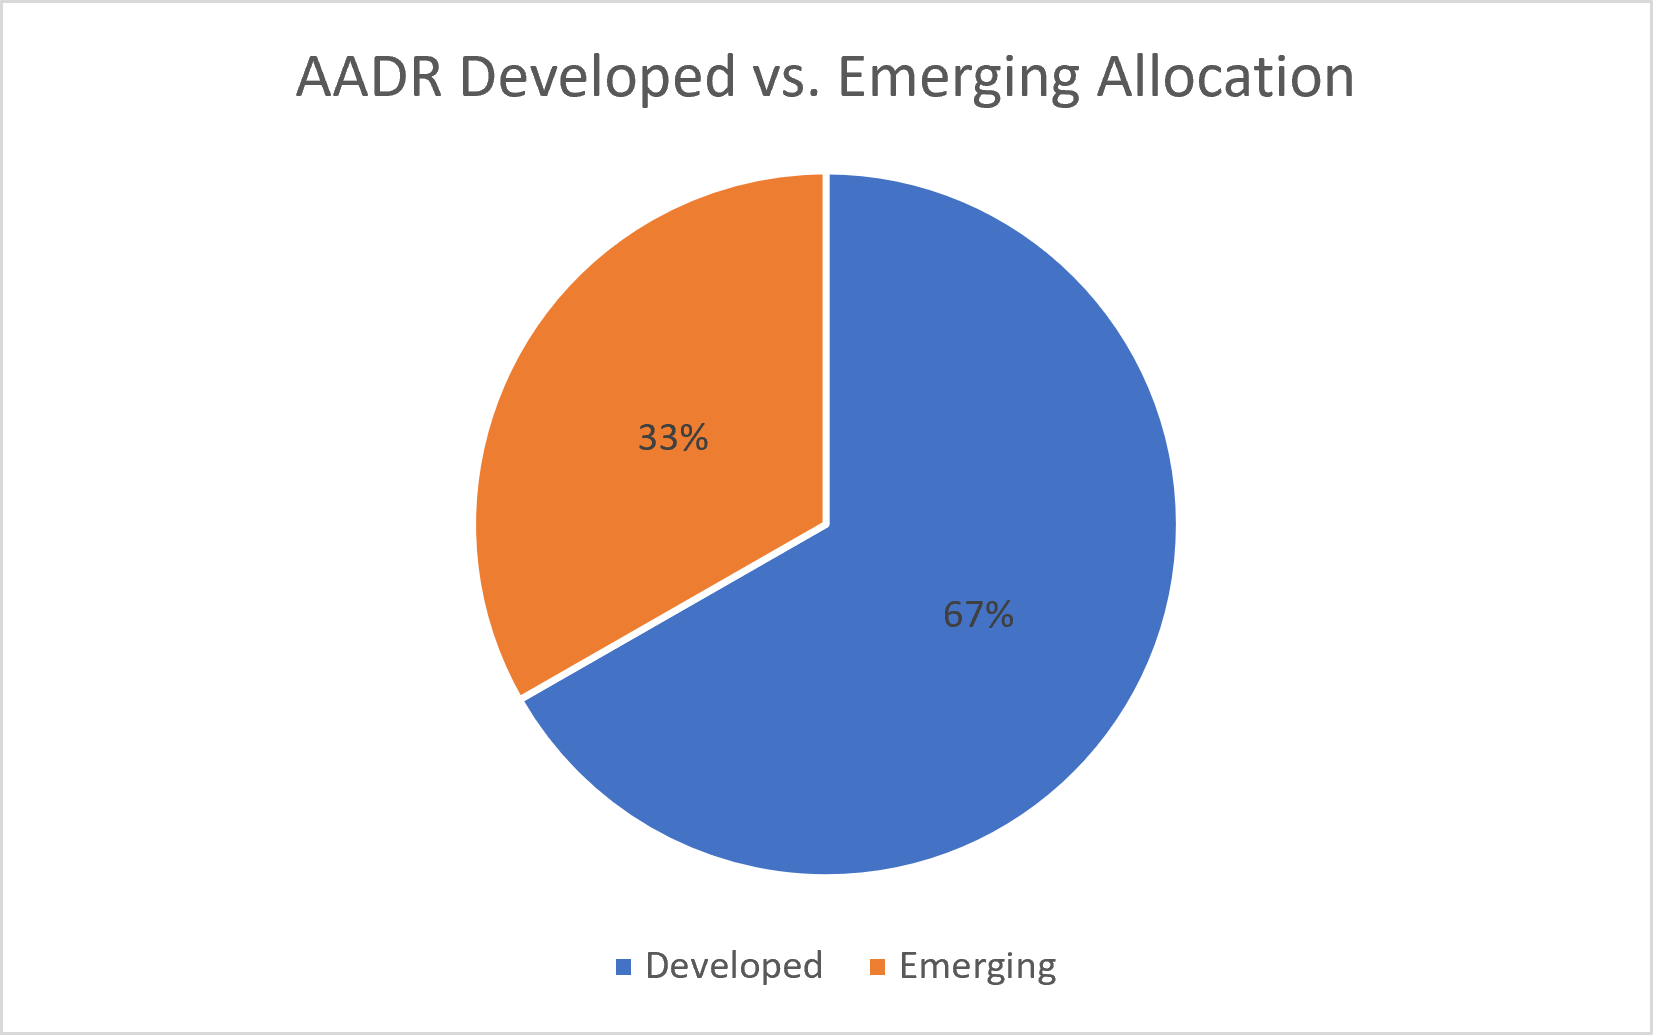
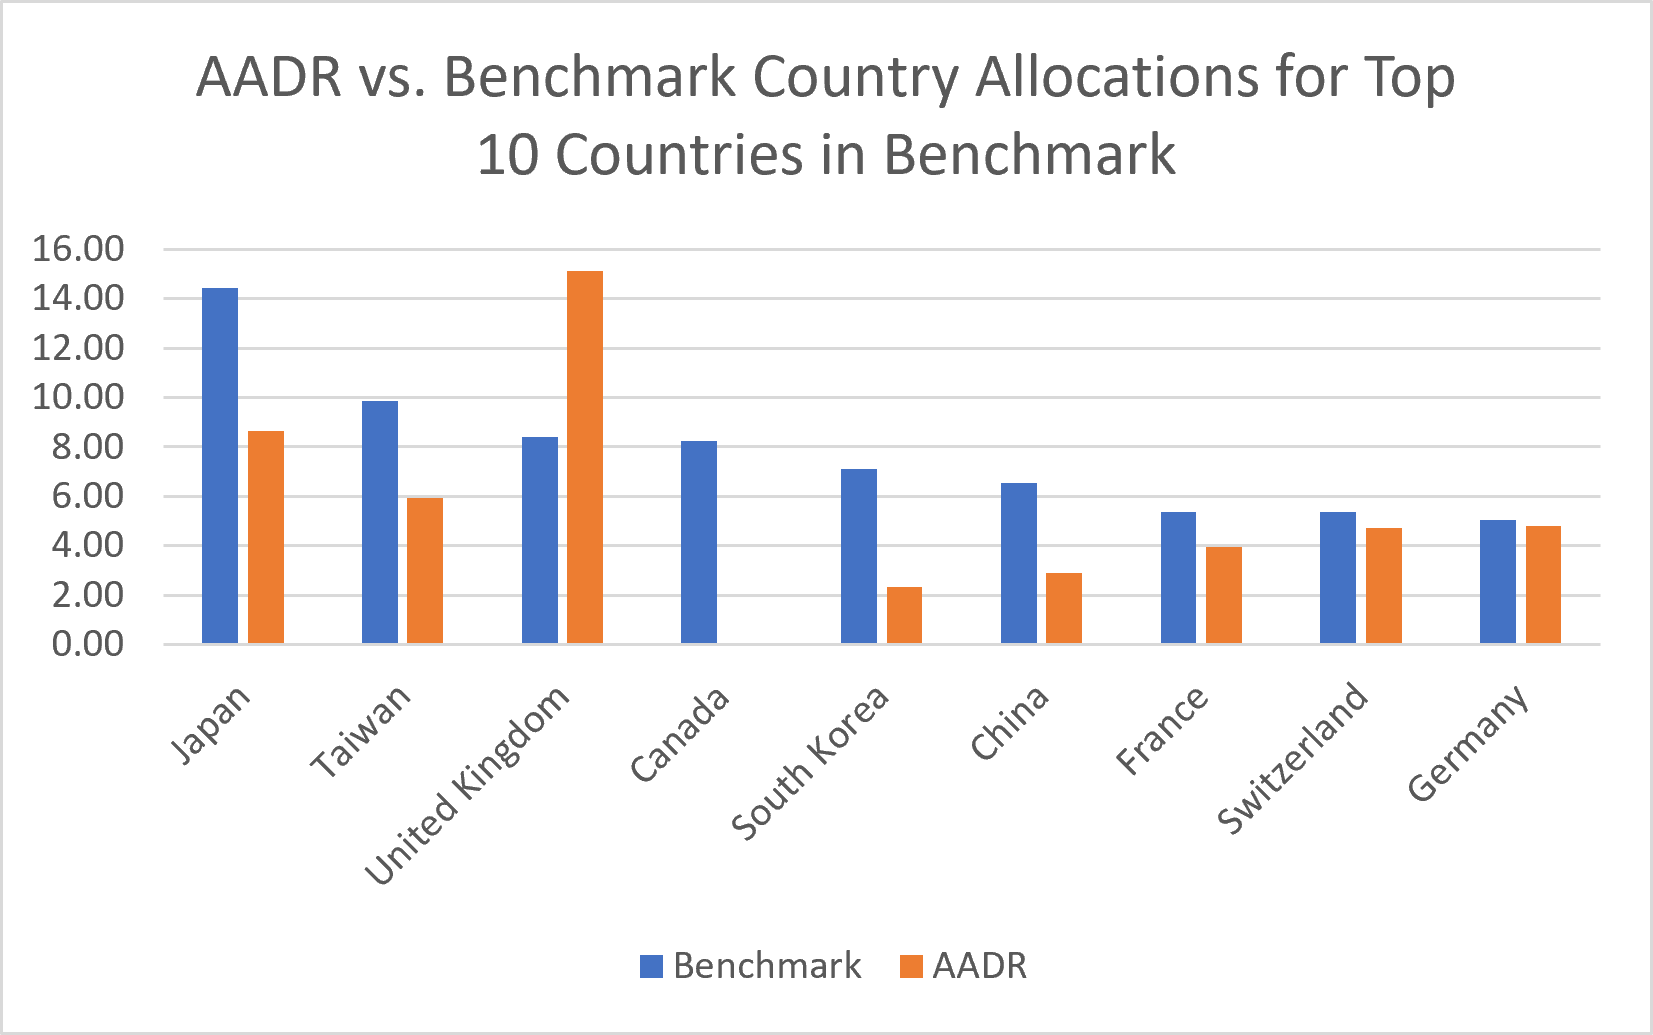
The portfolio’s process of focusing on sectors and the strength of holdings allows the portfolio to look much different than the broad market benchmark.  The current allocation also looks different when comparing Developed Market vs. Emerging Market exposure.  The portfolio currently holds more Developed vs. Emerging (66.70% vs. 33.27%).  The country allocations are also substantially different.  As can be seen below, AADR holds no exposure to Canada and reduced exposure to Japan and Taiwan which are both large weights in the benchmark.  Instead, we have excess allocations to countries like the United Kingdom and other smaller countries where we’ve still seen areas of relative strength in despite recent pullbacks.  At times we’ll own many countries which would never have large allocations in a passive benchmark.

As of 09.30.2026. Source: Nasdaq Dorsey Wright. Benchmark = MSCI ACWI ex-US Index.

Sector
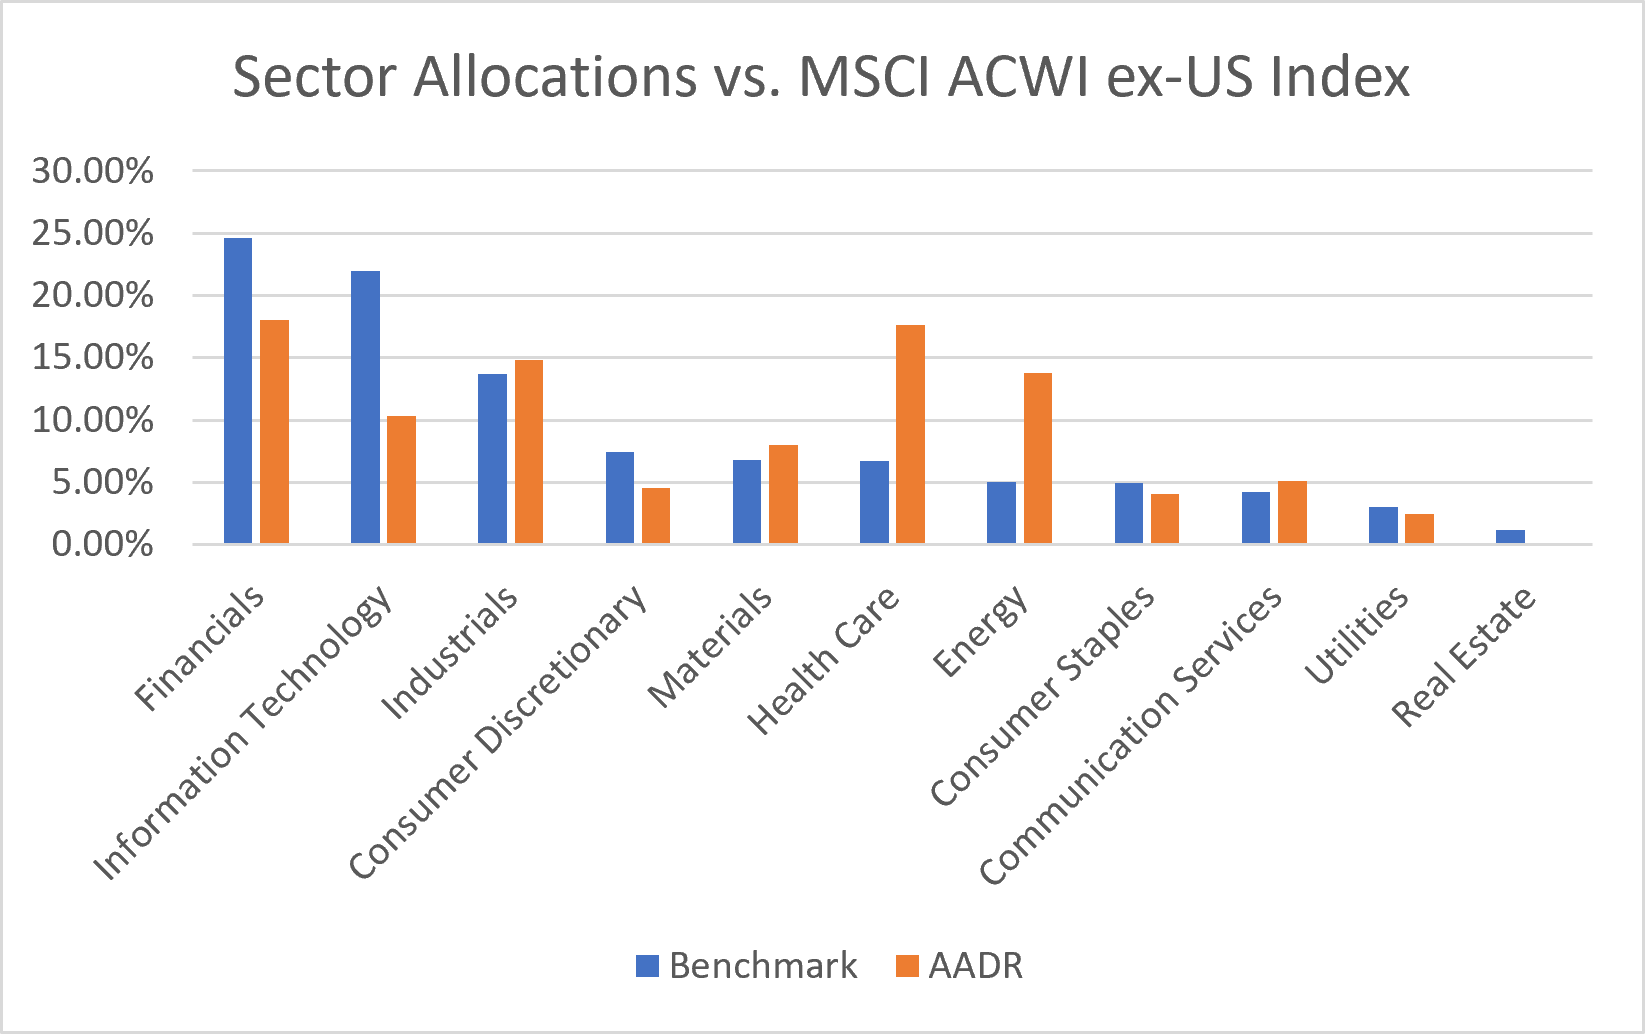
The buy/sell process of the strategy starts with a look at the strongest sectors within the universe, overweighting strength and underweighting or eliminating relative weakness. The portfolio continues to be actively allocated to sectors in a materially different way than the benchmark.  Notably, the portfolio is most overweight in Health Care, Energy, and Materials while most underweight in Technology, Financials, and Consumer Discretionary.

As of 09.30.2026. Source: Nasdaq Dorsey Wright. Benchmark = MSCI ACWI ex-US Index.
Respectfully,
John Lewis
John G. Lewis
Nasdaq Dorsey Wright
AdvisorShares Dorsey Wright ADR ETF (AADR) Portfolio Strategist

Past Commentary

Definitions: An American Depositary Receipt (ADR) is a negotiable U.S. Security that generally represents a company’s publicly traded equity or debt. Depositary Receipts are created when a broker purchases a non-U.S. company’s shares on its home stock market and delivers the shares to the depositary’s local custodian bank, and then instructs the depositary bank to issue Depositary Receipts. The MSCI All Country World Ex-U.S. Index (ACWI) is a free float adjusted market capitalization weighted index that is designed to measure the equity market performance of developed and emerging markets.


Before investing you should carefully consider the Fund’s investment objectives, risks, charges and expenses. This and other information is in the prospectus or summary prospectus, a copy of which may be obtained by visiting www.advisorshares.com. Please read the prospectus carefully before you invest. Foreside Fund Services, LLC, distributor.

There is no guarantee that the Fund will achieve its investment objective. An investment in the Fund is subject to risk, including the possible loss of principal amount invested. Emerging Markets, which consist of countries or markets with low to middle income economics can be subject to greater social, economic, regulatory and political uncertainties and can be extremely volatile. Other Fund risks include concentration risk, foreign securities and currency risk, ADRs which may be less liquid, large-cap risk, early closing risk, counterparty risk and trading risk, which can increase Fund expenses and may decrease Fund performance. The Fund is, also, subject to the same risks associated with the underlying ETFs, which can result in higher volatility. This Fund may not be suitable for all investors. See prospectus for detail regarding risk. Shares are bought and sold at market price (closing price) not NAV and are not individually redeemed from the Fund. Market price returns are based on the midpoint of the bid/ask spread at 4:00 pm Eastern Time (when NAV is normally determined), and do not represent the return you would receive if you traded at other times. Holdings and allocations are subject to risks and to change. The views in this commentary are those of the portfolio manager and may not reflect his views on the date this material is distributed or anytime thereafter. These views are intended to assist shareholders in understanding their investments and do not constitute investment advice.